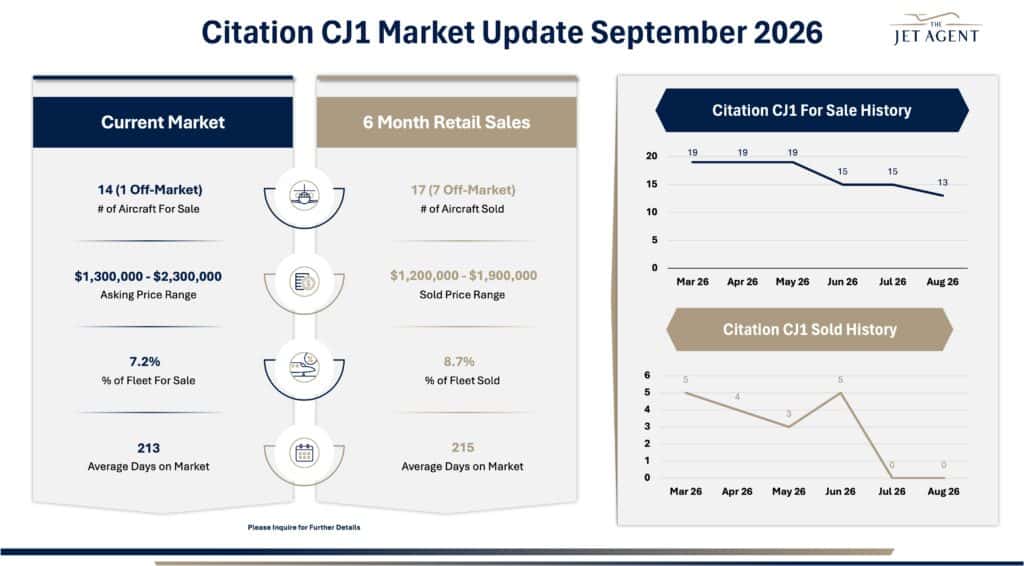
The Citation CJ1 market enters September with declining inventory but a noticeable pause in recent transaction activity. There are currently 14 aircraft available for sale, representing 7.2% of the fleet, compared with 17 retail sales over the past six months. Supply has moved steadily lower since the spring, but with no recorded sales in either July or August, the next few months will help determine whether the reduced inventory translates into renewed buyer activity.
Fleet Size and Availability
There are currently 14 Citation CJ1s available for sale, including 1 off-market aircraft, representing 7.2% of the fleet.
Inventory has declined considerably over the past several months. The market held at 19 aircraft for sale from March through May before dropping to 15 in June and July, followed by another decline to 13 aircraft in August. This reduction in available inventory is encouraging for sellers and leaves buyers with fewer options than they had earlier this year.
Market Listings
Current asking prices range from $1.3 million to $2.3 million, while the six-month sold price range is $1.2 million to $1.9 million. The overlap between current asking prices and recent transaction values provides a useful reference point, although individual aircraft values can vary considerably based on maintenance status, engine programs, total time, cosmetics, and overall condition.
Current listings average 213 days on market, nearly identical to the 215-day average for aircraft sold during the past six months. This suggests that roughly seven months of market exposure remains typical for the CJ1.
Sales Activity
There have been 17 retail sales over the past six months, including 7 off-market transactions, representing 8.7% of the fleet.
Sales activity was relatively healthy through the first half of the period, with five transactions in March, four in April, three in May, and five in June. However, no retail sales were recorded in either July or August. That recent slowdown is worth watching, particularly given that inventory has continued to decline at the same time.
Key Takeaways
• 14 aircraft are currently available, representing 7.2% of the fleet.
• Available inventory has fallen meaningfully from spring levels.
• 17 aircraft sold during the past six months, representing 8.7% of the fleet.
• Seven of those 17 transactions occurred off-market.
• No retail sales were recorded during July or August.
• Current and sold aircraft have nearly identical average days on market.
Key Insight
The CJ1 presents an interesting balance heading into the fall. Six-month sales exceed current inventory, and the number of available aircraft has fallen significantly, both of which are constructive indicators. However, the absence of transactions during the past two months prevents the market from being characterized as particularly active today. Sellers should benefit from reduced competition, but realistic pricing remains important until buyer activity begins to accelerate again.