The Citation CJ1+ market enters September with limited inventory and relatively balanced six-month sales activity, although transaction volume has slowed recently. Only six aircraft are currently available for sale, representing 6.1% of the fleet, compared with seven retail transactions over the past six months. Inventory has steadily declined since March, creating a relatively tight selection for buyers, but the lack of a sale in August suggests demand remains selective.
Fleet Size and Availability
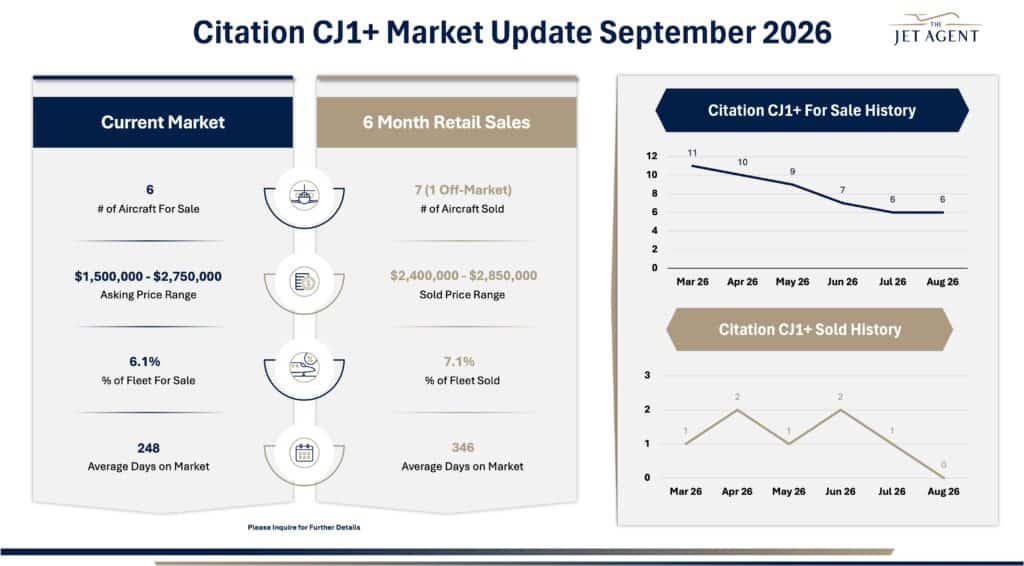
There are currently 6 Citation CJ1+ aircraft available for sale, representing 6.1% of the fleet.
Inventory has consistently moved lower throughout the reporting period. There were 11 aircraft for sale in March, followed by 10 in April, nine in May, seven in June, and six in both July and August. This represents a meaningful reduction in available supply and leaves buyers with nearly half as many options as they had entering the spring.
Market Listings
Current asking prices range from $1.5 million to $2.75 million, while the six-month sold price range is considerably tighter at $2.4 million to $2.85 million. With only six aircraft currently available, individual aircraft differences can have an outsized impact on the overall asking-price range.
Current listings average 248 days on market, compared with 346 days for aircraft sold during the past six months. The fact that recently sold aircraft spent considerably longer on market than today’s available inventory suggests that some transactions are occurring only after extended exposure.
Sales Activity
There have been 7 retail sales over the past six months, including 1 off-market transaction, representing 7.1% of the fleet.
Monthly sales have remained modest, with one transaction in March, two in April, one in May, two in June, one in July, and no sales in August. While total six-month sales slightly exceed today’s available inventory, there has not yet been enough monthly volume to establish sustained momentum.
Key Takeaways
• Only six aircraft are currently available, representing 6.1% of the fleet.
• Inventory has declined from 11 aircraft in March to six in August.
• Seven aircraft sold during the past six months, representing 7.1% of the fleet.
• No retail transactions were recorded in August.
• Current listings average 248 DOM versus 346 days for recently sold aircraft.
• Six-month sales slightly exceed current available inventory.
Key Insight
The CJ1+ market remains relatively tight from an inventory standpoint, with available supply nearly cut in half since March. That limited selection can work in favor of well-positioned sellers, but the recent sales pace shows that buyers are not necessarily rushing to transact simply because fewer aircraft are available. With only seven six-month sales and no transaction recorded in August, pricing and overall aircraft quality remain important in converting limited supply into actual buyer demand.