The Citation XLS Gen2 market enters September with inventory steadily increasing while transaction activity has recently slowed. Five aircraft are currently available for sale, compared with four retail transactions during the past six months. While five listings is a small number in absolute terms, it represents 8.3% of the relatively young XLS Gen2 fleet. With no recorded sales in either July or August, the relationship between growing availability and near-term buyer activity will be important to watch heading into the fall.
Fleet Size and Availability
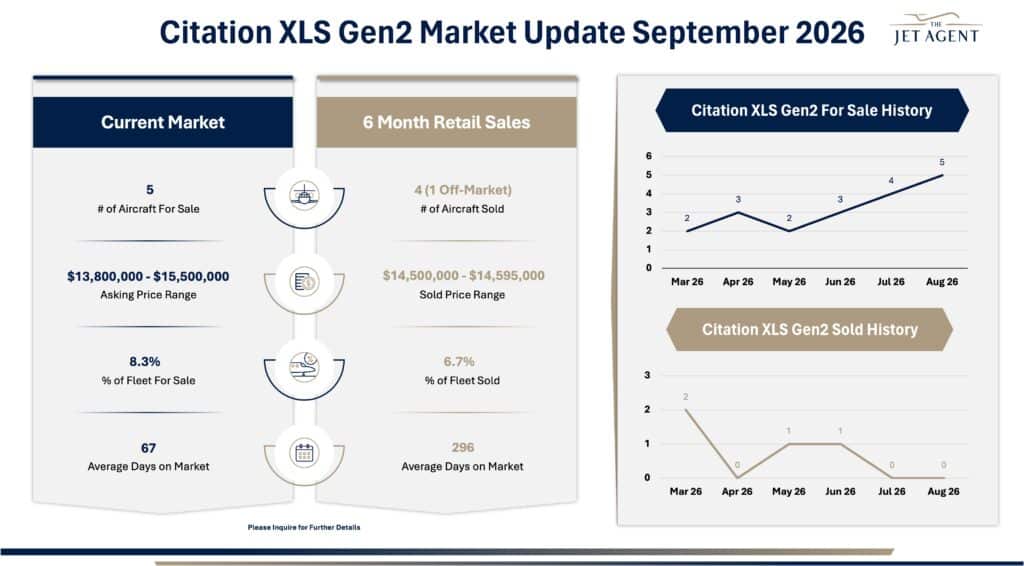
There are currently five Citation XLS Gen2s available for sale, representing 8.3% of the fleet.
Inventory has generally moved higher over the past several months. Two aircraft were available in March, increasing to three in April before returning to two in May. Supply then climbed consistently to three in June, four in July, and five in August.
The percentage of fleet for sale appears relatively high compared with some other late-model Citation markets, although the small fleet size means only a few aircraft can materially change that percentage.
Market Listings
Current asking prices range from $13.8 million to $15.5 million, while the four aircraft sold during the past six months ranged from $14.5 million to $14.595 million.
Current listings average just 67 days on market, significantly below the 296-day average for aircraft sold during the six-month period. That difference suggests today’s inventory is considerably fresher than the aircraft represented in the recent sales data.
With both the available fleet and transaction sample relatively small, individual aircraft specifications, year, total time, condition, and maintenance status can have a meaningful influence on pricing.
Sales Activity
There have been four retail transactions during the past six months, including one off-market sale, representing 6.7% of the fleet.
Two aircraft sold in March, followed by no transactions in April. One sale was recorded in both May and June, while July and August each recorded zero sales.
The recent slowdown comes as inventory has moved in the opposite direction, increasing from two aircraft in May to five in August.
What this means for you:
Inventory has risen for three consecutive months and there have been no sales in July or August. That combination deserves a straightforward read: the market has paused. It is a small fleet, so one or two transactions will change the statistics quickly, but sellers cannot ignore the direction of travel. If you are considering a sale, the current asking range of $13.8M to $15.5M sits below where the last four aircraft actually sold, between $14.5M and $14.595M. That is an unusual and meaningful signal: recent buyers paid more than sellers are currently asking. Pricing to that sold range, not below it, is where the data points. If you are a buyer, inventory is the most available it has been all period and sellers are pricing below recent transaction history. The data favors you right now, but that window will close the moment sales activity resumes.