The Phenom 300E market remains relatively balanced entering September, with limited inventory and consistent transaction activity over the past six months. There are currently 12 aircraft available for sale, representing just 2.8% of the fleet, while 18 aircraft have sold during the six-month reporting period. Inventory has fluctuated within a fairly narrow range, while August delivered the strongest sales month of the period.
Fleet Size and Availability
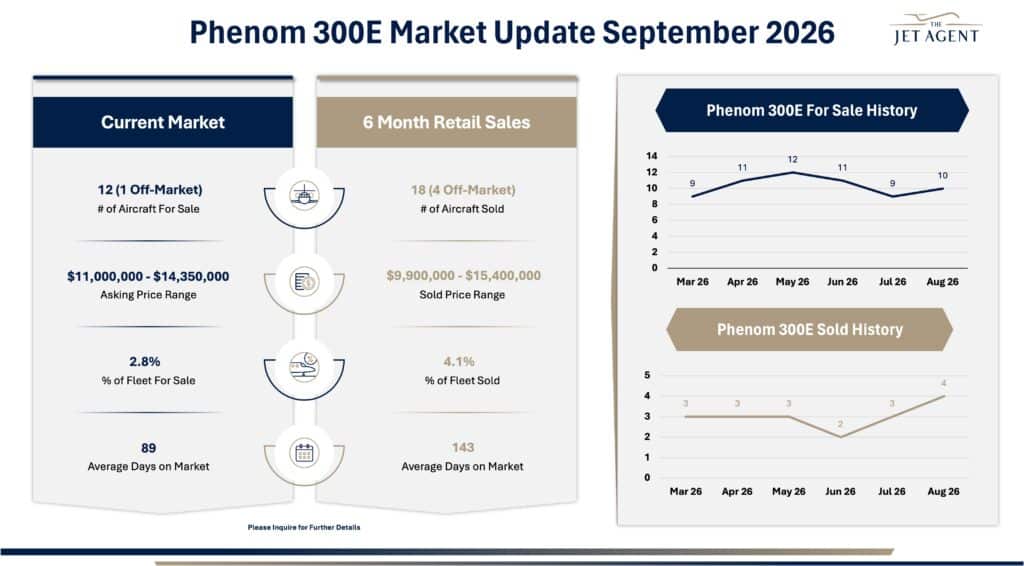
There are currently 12 Phenom 300E aircraft available for sale, including one off-market aircraft, representing 2.8% of the fleet.
Inventory has remained relatively stable over the past six months. The market began with nine aircraft for sale in March, increased to 11 in April and 12 in May, then moved back to 11 in June and nine in July before increasing to 10 in August.
Unlike several markets where inventory has moved sharply in one direction, the Phenom 300E has maintained a relatively consistent level of availability.
Market Listings
Current asking prices range from $11.0 million to $14.35 million, while the 18 aircraft sold during the past six months traded between $9.9 million and $15.4 million.
Current listings average just 89 days on market, compared with 143 days for recently sold aircraft. This is an encouraging indicator for current sellers, suggesting that today’s available inventory is relatively fresh compared with the aircraft that have recently completed transactions.
With inventory representing less than 3% of the fleet, buyers continue to face a relatively limited selection of available aircraft.
Sales Activity
There have been 18 retail sales over the past six months, including four off-market transactions, representing 4.1% of the fleet.
Sales activity has also been notably consistent. Three aircraft sold in each of March, April and May before activity dipped slightly to two transactions in June. Sales returned to three in July before increasing to four transactions in August, the strongest month of the six-month period.
That recent increase is particularly notable because it occurred while advertised inventory remained below its May peak.
What this means for you:
The 300E has done something few markets manage: it has stayed consistent. Three sales a month from March through May, a brief dip to two in June, back to three in July, and four in August, which was the strongest month of the entire six-month period. Inventory has held in a narrow range throughout. This is a balanced market operating the way a balanced market should. If you are a seller, the 89-day average DOM for current listings versus 143 days for sold aircraft tells you well-positioned aircraft are moving faster than the historical average. That is an advantage, but it requires accurate pricing and strong presentation to capture. Aircraft that do not stand out will drift toward the 143-day average. If you are a buyer, 12 aircraft are available right now, which is reasonable selection for this segment. August’s four sales are worth noting though. At that pace, inventory absorbs quickly and options narrow. If you have identified aircraft you are serious about, the time to move is not after the field gets smaller.