The Citation CJ1 market enters October with inventory increasing following a summer decline, while publicly advertised sales activity has come to a standstill. There are currently 20 aircraft available for sale, representing 10.3% of the fleet, compared with 12 retail transactions over the past six months. Although transactions earlier in the reporting period demonstrated buyer interest, the absence of publicly marketed sales since June is worth watching. With inventory returning to levels seen earlier this spring, sellers may face increased competition heading into the final quarter of 2026.
Fleet Size and Availability
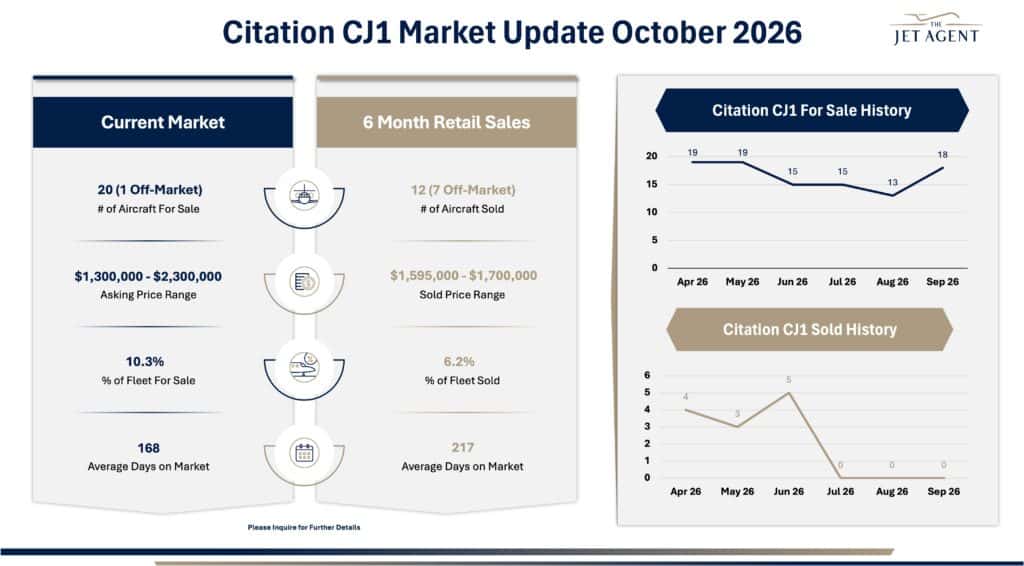
There are currently 20 Citation CJ1s available for sale, including one off-market aircraft, representing 10.3% of the fleet.
Inventory remained at 19 aircraft in April and May before declining to 15 in June and July, reaching a low of 13 in August. September brought a noticeable increase to 18 aircraft, reversing much of the inventory reduction experienced throughout the summer.
This recent increase suggests that buyers are gaining additional options, while sellers may need to work harder to differentiate their aircraft from competing listings.
Market Listings
Current asking prices range from $1.3 million to $2.3 million, while reported sales over the past six months ranged from $1.595 million to $1.7 million.
Aircraft currently available average 168 days on market, compared with 217 days for aircraft sold during the reporting period. Interestingly, sold aircraft spent an average of 49 more days on the market than current listings.
This difference suggests that buyers have been willing to consider aircraft with extended market exposure, although pricing, maintenance status, and overall condition remain important factors in determining which aircraft ultimately transact.
Sales Activity
The CJ1 market recorded 12 retail transactions over the past six months, including seven off-market sales, representing 6.2% of the fleet.
Monthly sales activity was strongest in June, with five transactions, following four in April and three in May. However, no additional transactions were recorded in July, August, or September.
The lack of recent sales is notable, particularly as inventory has begun increasing again. With seven of the 12 transactions occurring off-market, privately negotiated transactions have represented a substantial portion of recent market activity.
Key Takeaways
• 20 aircraft are currently available, representing 10.3% of the fleet.
• Inventory increased from 13 aircraft in August to 18 in September.
• 12 aircraft sold during the past six months, including seven off-market transactions.
• Current asking prices range from $1.3 million to $2.3 million.
• Reported sales ranged from $1.595 million to $1.7 million.
• Current listings average 168 DOM, compared with 217 days for sold aircraft.
• No retail transactions were recorded during July, August, or September.
Key Insight
The Citation CJ1 market is entering the fourth quarter with a growing inventory and a noticeable slowdown in transaction activity. While the first half of the reporting period produced consistent sales, the absence of transactions over the past three months raises questions about near-term buyer demand. At the same time, inventory has rebounded from its August low, creating additional competition among sellers. With more than 10% of the fleet currently available, realistic pricing and strong aircraft presentation will be especially important. Sellers considering a transaction before year-end should evaluate their aircraft against current competition rather than relying solely on historical sales prices. Buyers, meanwhile, may find increased opportunities to negotiate as available inventory grows and sellers reassess their expectations.