The Citation CJ1+ market enters October with inventory holding steady and transaction activity slowing considerably. There are currently six aircraft available for sale, representing 6.1% of the fleet, while six retail transactions have been recorded over the past six months. Although inventory has declined from earlier this spring, the absence of sales during August and September suggests that buyers remain selective. With both current listings and recently sold aircraft showing extended days on market, sellers should pay particular attention to pricing, aircraft condition, and competitive positioning as we enter the final quarter of 2026.
Fleet Size and Availability
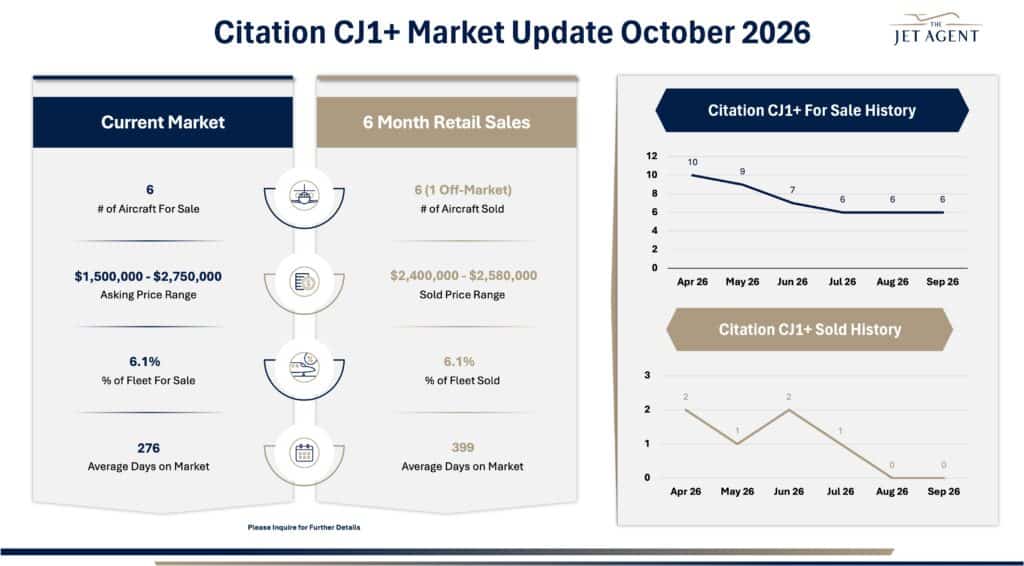
The CJ1+ market currently has six aircraft available for sale, representing 6.1% of the active fleet. Inventory has declined steadily from ten aircraft in April to nine in May and seven in June, before reaching six in July. Availability has remained unchanged through August and September.
While the reduction in inventory would typically suggest a tightening market, the lack of recent transactions indicates that lower availability has not necessarily translated into stronger buyer demand.
Market Listings
Current asking prices range from $1.5 million to $2.75 million, while recorded sales over the past six months ranged from $2.4 million to $2.58 million.
Aircraft currently listed for sale average 276 days on market, compared with 399 days for aircraft sold during the reporting period. This 123-day difference is significant, suggesting that completed transactions have involved aircraft with considerable market exposure.
The relatively narrow range of reported selling prices, compared with the broader asking price range, also highlights the importance of evaluating each aircraft individually rather than relying on advertised prices alone.
Sales Activity
Over the past six months, six CJ1+ aircraft have sold, including one off-market transaction, representing 6.1% of the fleet.
Monthly sales activity included two transactions in April, one in May, two in June, and one in July. No additional transactions were recorded in August or September.
Although the market has demonstrated an ability to absorb available inventory, the recent slowdown suggests that buyers may be taking additional time to evaluate opportunities before committing to a purchase.
Key Takeaways
• Six aircraft are currently available, representing 6.1% of the fleet.
• Inventory declined from ten aircraft in April to six in July and has remained unchanged since.
• Six retail transactions were recorded over the past six months, including one off-market sale.
• Asking prices range from $1.5 million to $2.75 million.
• Reported selling prices range from $2.4 million to $2.58 million.
• Current listings average 276 DOM, compared with 399 days for sold aircraft.
• No sales were recorded during August or September.
Key Insight
The Citation CJ1+ market presents an interesting balance heading into the fourth quarter. Inventory remains relatively limited, but recent sales activity has stalled, suggesting that reduced supply alone is not enough to motivate buyers. Extended days on market for both active listings and completed transactions indicate that patience remains an important factor for sellers. With 6.1% of the fleet currently available and an equal percentage having sold during the past six months, the market is not experiencing an overwhelming supply imbalance. However, buyers appear willing to wait for aircraft that meet their expectations for condition, maintenance status, and value. Sellers looking to complete a transaction before year-end should focus on realistic pricing and ensuring their aircraft stands out among the available options.