The CJ3+ is becoming a harder market to shop. September produced six sales (the strongest month of the past six months) and current availability is down to 12 aircraft, or 3.8% of the fleet. With 20 sales over that period, buyers are seeing their alternatives narrow. For buyers whose budget limits them to a particular serial number range, only a portion of those 12 aircraft may be realistic candidates. Factor in equipment, maintenance status, and aircraft history, and the shortlist can narrow quickly.
Sellers with well-maintained, realistically priced aircraft have a stronger position, but buyers still need a reason to choose their aircraft. For buyers, the advantage is preparation: know your requirements and recent comparable sales so you can move confidently when the right CJ3+ becomes available.
Fleet Size and Availability
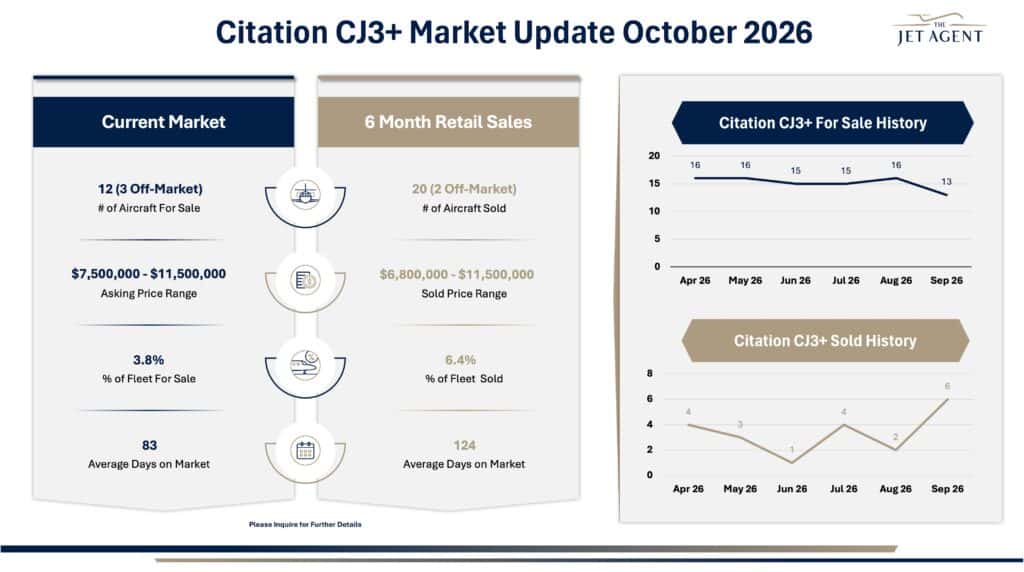
The CJ3+ market currently has 12 aircraft available for sale, including three off-market offerings, representing just 3.8% of the fleet.
Inventory remained relatively stable throughout much of the reporting period, beginning at 16 aircraft in April and May before declining to 15 in June and July. Availability briefly returned to 16 in August before falling to 13 by the end of September.
This represents a meaningful reduction in available inventory, particularly when considering the consistent sales activity recorded over the same period. With fewer aircraft available, buyers find their options increasingly limited.
Market Listings
Current asking prices range from $7.5 million to $11.5 million, while completed transactions over the past six months have ranged from $6.8 million to $11.5 million.
Active listings currently average 83 days on market, compared with 124 days for completed sales. This relatively low average for current inventory suggests that many available aircraft are newer listings, although individual marketing periods will vary.
Sales Activity
Over the past six months, 20 CJ3+ aircraft have sold, representing 6.4% of the fleet.
Monthly transaction activity included four sales in April, three in May, one in June, four in July, two in August, and six in September.
September’s six transactions marked the strongest month of the reporting period and a significant improvement over August’s two sales. This late-quarter increase is particularly encouraging given the simultaneous reduction in available inventory.
With six-month sales volume exceeding current inventory, the CJ3+ market is demonstrating healthy absorption. Continued transaction activity at similar levels could place additional pressure on available supply, particularly for desirable aircraft.
Key Takeaways
• 12 aircraft are currently available, including three off-market offerings.
• Available inventory represents just 3.8% of the fleet.
• September inventory declined to 13 aircraft, down from 16 in August.
• Current asking prices range from $7.5 million to $11.5 million.
• 20 aircraft sold over the past six months, representing 6.4% of the fleet.
• Completed transactions ranged from $6.8 million to $11.5 million.
• Active listings average 83 days on market, compared with 124 days for completed sales.
• September recorded six transactions, the strongest monthly performance over the period.
Key Insight
The CJ3+ market is giving sellers more leverage, but buyers are still choosing carefully. Six September sales and a narrowing selection strengthen the position of owners offering well-maintained aircraft at prices supported by recent transactions. Limited competition helps; it does not make an ambitious asking price easier to justify.
For buyers, the practical question is how many of the 12 available aircraft actually fit. A budget tied to a particular serial number range may eliminate much of the inventory before equipment, maintenance status, and history enter the discussion. Three aircraft are offered off-market, so a search limited to public listings also misses part of the selection.
Waiting until Q1 does not necessarily mean buying for less. Buyers pressing to meet a December 31 bonus depreciation deadline may pay premiums to secure an aircraft in time. Those higher closing prices become the next comparable sales, potentially lifting seller expectations and supporting higher valuations into the new year. A patient buyer could avoid the year-end competition only to face a higher pricing baseline.
The sensible approach is to establish your priorities, understand comparable sales, and be ready to evaluate a suitable aircraft promptly. Sellers should use reduced competition to position their aircraft well from the outset, while buyers should weigh the cost of waiting alongside the possibility of finding a better deal.