The Citation CJ3 remains a healthy and liquid market, but August’s increase in inventory has given buyers more choice than they had earlier this summer. Twenty aircraft have sold during the past six months while 27 are currently available. Transaction activity remains dependable, and the relatively small difference between active and sold-aircraft days on market suggests the market is still functioning efficiently rather than becoming materially oversupplied.
Fleet Size and Availability
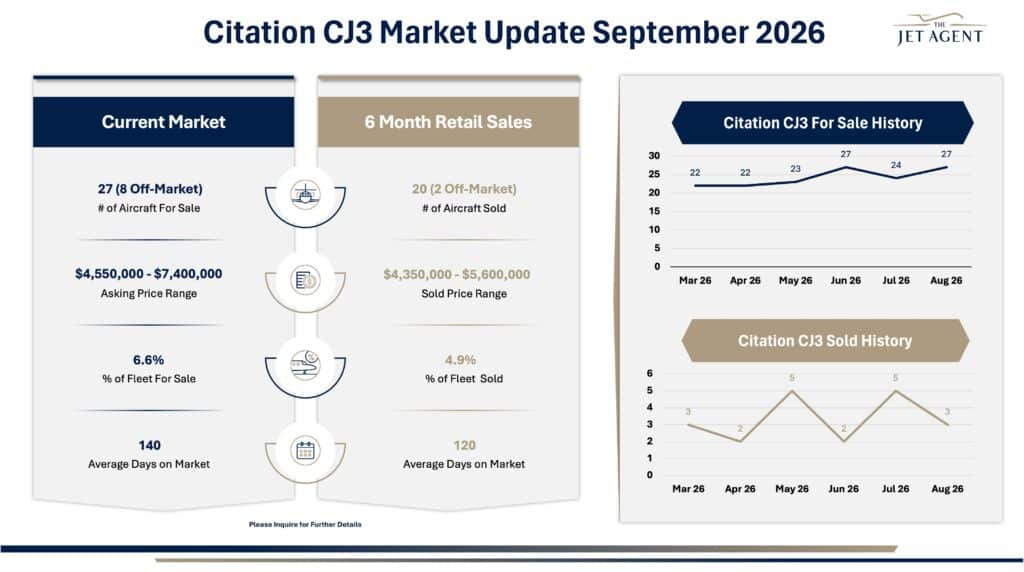
There are currently 27 Citation CJ3s available for sale, including 8 off-market aircraft, representing 6.6% of the fleet.
Inventory stood at 22 aircraft in March and April, increased to 23 in May, reached 27 in June, declined to 24 in July, and returned to 27 in August. At 6.6% of the fleet, current supply is not excessive, but the move back to the six-month high is worth monitoring as the fall market develops.
The practical effect is greater choice for buyers and more competition among sellers, while the overall level of supply remains consistent with an active market.
Market Listings
Current asking prices range from $4.55 million to $7.4 million, compared with a six-month sold price range of $4.35 million to $5.6 million.
Current listings average 140 days on market, while sold aircraft averaged 120 days. The 20-day difference is modest and suggests current inventory has not yet accumulated meaningful staleness.
The wider separation between the upper end of current asking prices and recent transaction history is more notable. Buyers should evaluate individual aircraft based on model year, total time, maintenance status, engine programs, equipment, cosmetics, and overall condition rather than relying on advertised price alone.
Sales Activity
The CJ3 recorded 20 retail sales during the past six months, including 2 off-market transactions, representing 4.9% of the fleet.
Sales remained consistent throughout the period: three in March, two in April, five in May, two in June, five in July, and three in August. Every month produced multiple transactions, demonstrating continued buyer participation even as inventory fluctuated.
August’s three sales were below July’s five but remained consistent with the broader six-month pace.
Key Takeaways
• 27 aircraft are currently available, including 8 off-market opportunities.
• Current inventory represents 6.6% of the fleet.
• 20 aircraft sold over the past six months, including 2 off-market transactions.
• Every month during the period recorded multiple transactions.
• Current listings average 140 DOM versus 120 days for sold aircraft.
• Inventory has returned to its six-month high, giving buyers more selection without yet signaling material oversupply.
Key Insight
The CJ3 continues to be one of the healthier Citation markets, with consistent transaction activity and a relatively efficient relationship between current and sold-aircraft market time. The return of inventory to 27 aircraft is beginning to give buyers more choice, but the market has not yet developed the characteristics of oversupply: every month has produced multiple transactions and the DOM spread remains modest. If inventory continues to build without a corresponding increase in sales this fall, leverage could shift further toward buyers. For now, the market remains active, liquid, and increasingly competitive for sellers.