The Citation CJ market enters September with elevated inventory and improving late-summer sales activity. There are currently 39 aircraft available for sale, representing 11.7% of the fleet, compared with 17 retail sales over the past six months. While August produced a welcome rebound in transactions, overall supply remains high relative to recent absorption, continuing to give buyers considerable choice.
Fleet Size and Availability
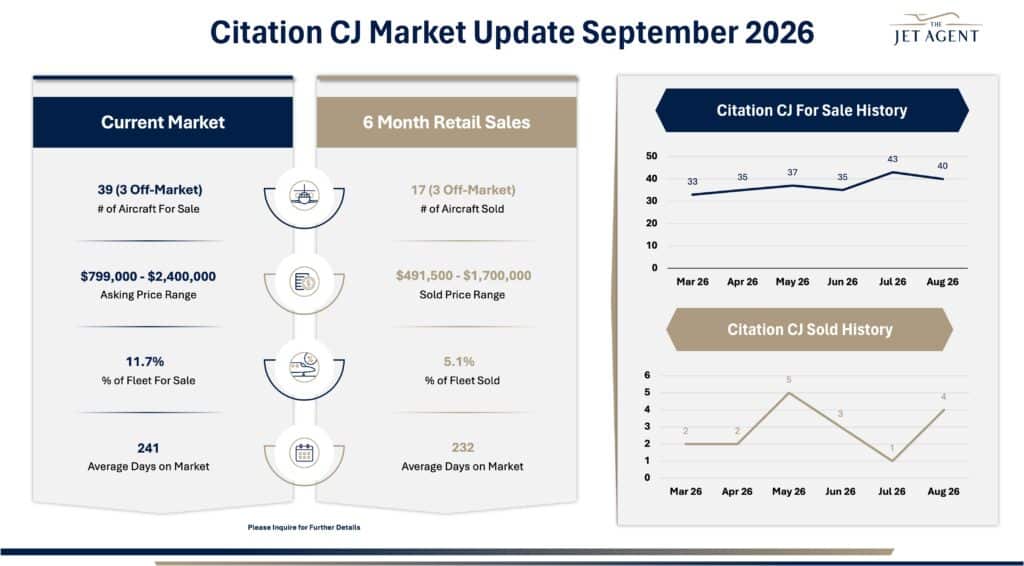
There are currently 39 Citation CJs available for sale, including 3 off-market aircraft, representing 11.7% of the fleet.
Inventory has generally trended higher over the past six months. The market moved from 33 aircraft for sale in March to 35 in April, 37 in May, and 35 in June before climbing sharply to 43 in July. Inventory eased to 40 aircraft in August, but remains noticeably above spring levels. For sellers, this means competition remains significant despite the modest improvement from July.
Market Listings
Current asking prices range from $799,000 to $2.4 million, while the six-month sold price range is $491,500 to $1.7 million. The wide spread reflects the meaningful differences in age, condition, maintenance status, engine programs, and overall aircraft configuration found throughout the CJ fleet.
Current listings average 241 days on market, compared with 232 days for aircraft sold during the past six months. With both figures approaching eight months, buyers continue to have time to evaluate alternatives, making accurate positioning and presentation especially important.
Sales Activity
There have been 17 retail sales over the past six months, including 3 off-market transactions, representing 5.1% of the fleet.
Monthly sales totaled two in March, two in April, five in May, three in June, one in July, and four in August. The August rebound is encouraging following July’s single transaction, although six-month sales remain well below the number of aircraft currently available.
Key Takeaways
• 39 aircraft are currently available, representing 11.7% of the fleet.
• Inventory remains elevated despite declining from its July peak.
• 17 aircraft sold during the past six months, equal to 5.1% of the fleet.
• August activity improved substantially with four transactions.
• Current listings average 241 DOM versus 232 days for sold aircraft.
• Supply continues to outweigh recent sales activity, creating a competitive environment for sellers.
Key Insight
The CJ remains a buyer-friendly market, with more than twice as many aircraft currently available as have sold during the past six months. August’s improvement in sales is a positive development, but one stronger month is not yet enough to materially change the supply-demand balance. With 11.7% of the fleet currently for sale and average market time above 240 days, sellers should expect buyers to be selective. Aircraft that are realistically priced, well maintained, and properly positioned against competing inventory should have the best opportunity to capture demand as activity moves into the fall.