The Citation Encore remains a selective, aircraft-specific market with considerably more supply than recent transaction volume would suggest. There are currently 13 aircraft available, while only 4 retail sales have occurred during the past six months. All four of those transactions took place in July. August returned to zero sales, confirming that July was an isolated burst of activity rather than evidence of a sustained market recovery.
Fleet Size and Availability
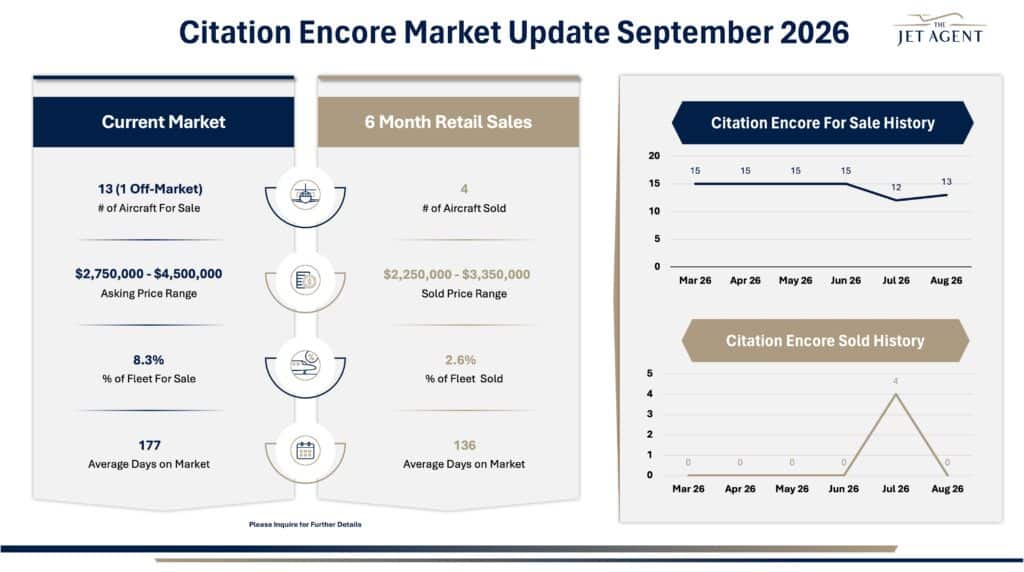
There are currently 13 Citation Encores available for sale, including 1 off-market aircraft, representing 8.3% of the fleet.
Inventory remained at 15 aircraft from March through June, declined to 12 in July, and increased slightly to 13 in August. Overall, supply has changed relatively little during the period and remains substantial when compared with recent absorption.
With 8.3% of the fleet available versus only 2.6% sold during the past six months, buyers continue to have considerable choice.
Market Listings
Current asking prices range from $2.75 million to $4.5 million, compared with a six-month sold price range of $2.25 million to $3.35 million.
Current inventory averages 177 days on market, while the four recently sold aircraft averaged 136 days. The upper end of current asking prices extends well above recent transaction history, making aircraft-specific maintenance and condition particularly important.
For the Encore, engine status remains one of the largest value drivers. Engine program enrollment and remaining time to hot section inspection or overhaul can materially affect both marketability and value, especially when buyers are comparing similarly priced aircraft.
Sales Activity
Only 4 retail sales were recorded during the past six months, representing 2.6% of the fleet.
All four transactions occurred in July. No retail sales were recorded in March, April, May, June, or August.
That pattern makes July an isolated surge rather than the beginning of a confirmed improvement in demand. August’s return to zero transactions, accompanied by a slight increase in inventory, reinforces the need to treat this as a highly selective market.
Key Takeaways
• 13 aircraft are currently available, including 1 off-market opportunity.
• 8.3% of the fleet is for sale versus just 2.6% sold over the past six months.
• All 4 six-month transactions occurred during July.
• August returned to zero recorded sales.
• Current inventory averages 177 DOM versus 136 days for sold aircraft.
• Engine program status and remaining time to major engine events remain critical value drivers.
Key Insight
The Encore market continues to favor patient, selective buyers rather than sellers relying on broad market momentum. July’s four transactions were encouraging, but August confirmed that they were an isolated burst rather than a sustained acceleration in demand. With supply remaining relatively steady and transaction volume sporadic, sellers need to compete on aircraft-specific fundamentals: realistic pricing, engine coverage, maintenance status, upcoming engine events, condition, and presentation. Buyers have time and alternatives on their side.