The Citation Excel market enters September with relatively limited inventory and steady six-month transaction volume, although sales activity has slowed considerably from its late-spring pace. There are currently 16 aircraft available for sale, representing 4.7% of the fleet, compared with 19 retail transactions during the past six months. Inventory recovered somewhat during July after reaching a six-month low in June, but remains below the levels seen earlier this spring.
Fleet Size and Availability
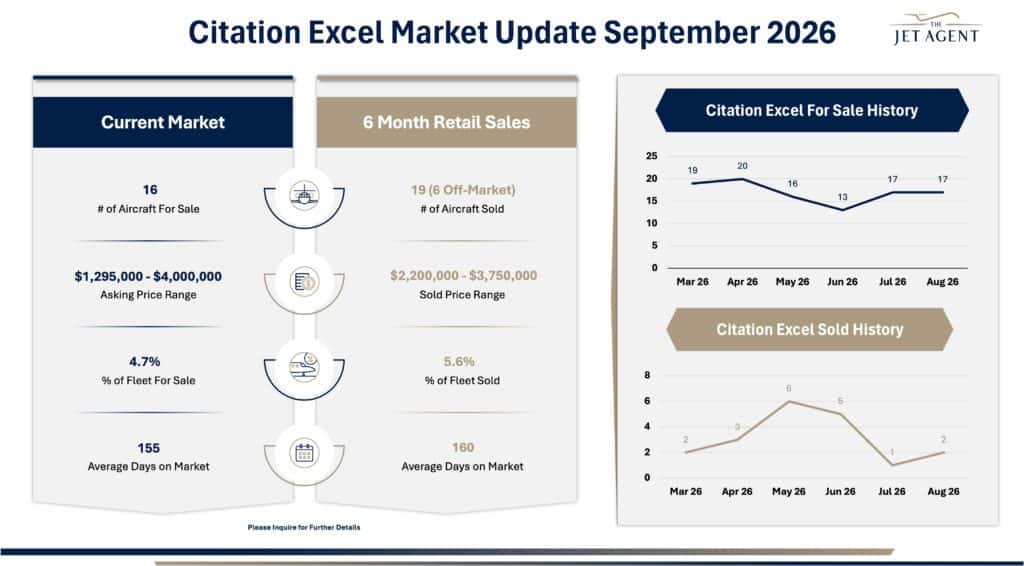
There are currently 16 Citation Excels available for sale, representing 4.7% of the fleet.
Inventory began the period at 19 aircraft in March and increased slightly to 20 in April before declining to 16 in May and just 13 in June. Supply then increased to 17 aircraft in July and remained at 17 in August. Despite that recent increase, available inventory remains relatively limited as a percentage of the overall fleet.
Market Listings
Current asking prices range from $1.295 million to $4.0 million, while aircraft sold during the past six months have ranged from $2.2 million to $3.75 million.
The wide asking-price range reflects the variation that exists within the Excel fleet, making individual aircraft specifications, maintenance status, engine programs, total time, and overall condition important when evaluating value.
Current listings average 155 days on market, compared with 160 days for aircraft sold during the past six months. The nearly identical figures suggest roughly five months of market exposure has been typical for both current inventory and completed transactions.
Sales Activity
There have been 19 retail sales during the past six months, including 6 off-market transactions, representing 5.6% of the fleet.
Transaction activity was strongest during May and June, when six and five aircraft sold, respectively. Activity slowed sharply during the summer, with only one sale in July and two in August. While the six-month total remains healthy relative to current inventory, the recent slowdown is worth watching as the market moves into the fall.
What this means for you:
The summer slowdown is real. Eleven sales in May and June gave way to just three in July and August, and inventory has climbed back from its June low. If you are considering selling, the market has not turned against you, but it is less forgiving than it was three months ago. With current and sold DOM nearly identical at 155 versus 160 days, buyers are not in a rush and neither are they disappearing. Price it accurately from the start and the market will work. Push it and you will become part of the stale inventory the data is already showing. If you are a buyer, you have more selection than you did in June and less competition than you did in the spring. This is a reasonable window to evaluate carefully without being forced into a quick decision.