The Citation CJ2+ market enters October with inventory at its lowest level in six months and sales activity showing signs of recovery. There are currently nine aircraft available for sale, representing just 4.1% of the fleet, while 18 retail transactions have been recorded over the past six months. Inventory has declined steadily from 20 aircraft in April, a reduction of 55%, indicating a meaningful tightening in available supply. Following a strong stretch of sales activity through July, transactions slowed considerably in August before recovering modestly in September. While reduced inventory is encouraging for sellers, the significant difference between current and sold aircraft days on market suggests that pricing and market positioning remain important factors heading into the fourth quarter.
Fleet Size and Availability
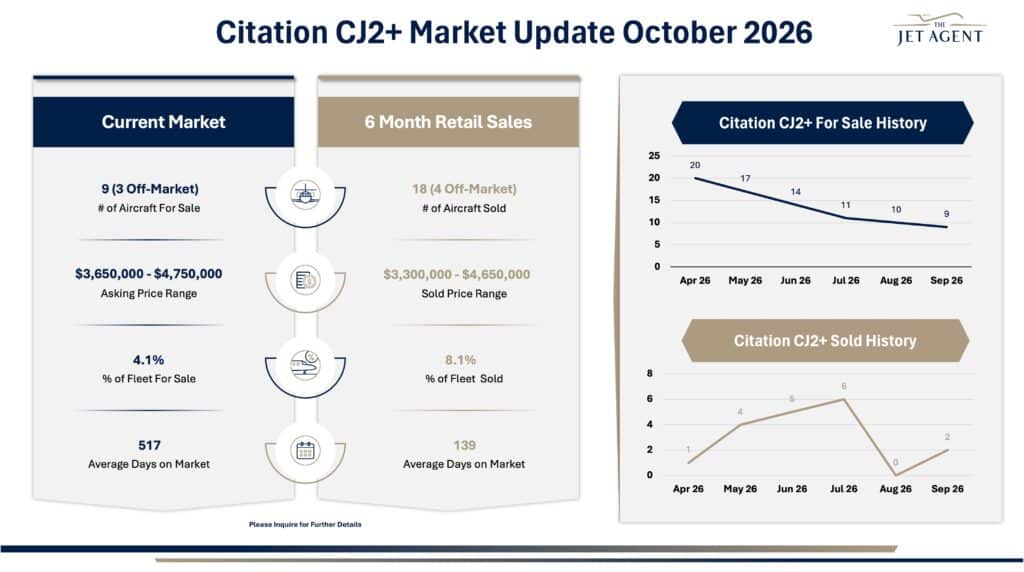
The CJ2+ market currently has nine aircraft available for sale, including three off-market offerings, representing 4.1% of the fleet.
Inventory has declined consistently throughout the reporting period, falling from 20 aircraft in April to 17 in May, 14 in June, 11 in July, ten in August, and nine in September.
This steady reduction in availability represents one of the more notable trends in the CJ2+ market. With fewer aircraft available for buyers to consider, well-positioned listings may benefit from reduced competition. However, the pace of sales will ultimately determine whether this tightening inventory translates into stronger pricing.
Market Listings
Current asking prices range from $3.65 million to $4.75 million, while completed transactions over the past six months ranged from $3.3 million to $4.65 million.
Aircraft currently listed for sale average 517 days on market, compared with just 139 days for aircraft sold during the reporting period. This substantial 378-day difference is particularly noteworthy.
While recently sold aircraft have generally completed transactions within a considerably shorter timeframe, the remaining inventory has accumulated significant market exposure. This suggests that some current listings may face challenges related to pricing, condition, maintenance status, or other aircraft-specific factors.
Sales Activity
Over the past six months, 18 CJ2+ aircraft have sold, including four off-market transactions, representing 8.1% of the fleet.
Monthly sales included one transaction in April, four in May, five in June, and six in July. Activity then slowed sharply, with no transactions recorded in August, before recovering to two sales in September.
The strong transaction volume between May and July likely contributed to the substantial reduction in available inventory. Although activity has cooled since its summer peak, September’s results provide some encouragement following August’s inactivity.
Key Takeaways
• Nine aircraft are currently available, representing only 4.1% of the fleet.
• Inventory has declined 55% since April, falling from 20 aircraft to nine.
• 18 retail transactions were recorded over the past six months, including four off-market sales.
• Asking prices range from $3.65 million to $4.75 million.
• Reported selling prices range from $3.3 million to $4.65 million.
• Current listings average 517 DOM, compared with 139 days for sold aircraft.
• September recorded two sales following zero transactions in August.
Key Insight
The CJ2+ market is short on fresh choices. Inventory has fallen 55% since April to nine aircraft, including three off-market opportunities, while 18 aircraft have sold over the past six months. Yet current listings average 517 days on market versus 139 days for sold aircraft. Together, those figures point to a market that has absorbed desirable opportunities while leaving a smaller pool of substantially older listings.
For sellers bringing a well-maintained, realistically priced CJ2+ to market, that creates an advantage: limited competition, particularly from fresh listings. Owners of long-standing listings face a different reality. Shrinking inventory has not produced a sale, and continued exposure alone is unlikely to resolve a mismatch in price, maintenance position, or condition.
For buyers, the nine-aircraft headline translates to just six publicly marketed choices before accounting for individual requirements. Older listings may offer negotiating room, but the aircraft’s maintenance exposure and upgrade costs determine whether a discount represents value. With only two sales in August and September combined, this is a selective market with limited supply—not one where every seller holds the upper hand.