The Citation CJ3 market enters October with a relatively balanced relationship between available inventory and recent sales activity. There are currently 24 aircraft available for sale, representing 5.9% of the fleet, while 22 retail transactions have been recorded over the past six months. Inventory has fluctuated throughout the reporting period but returned to its April level by the end of September. With consistent monthly sales and average days on market nearly identical between active listings and completed transactions, the CJ3 continues to demonstrate steady buyer interest. However, differences in aircraft condition, equipment, and pricing remain important considerations for sellers looking to stand out in a competitive marketplace.
Fleet Size and Availability
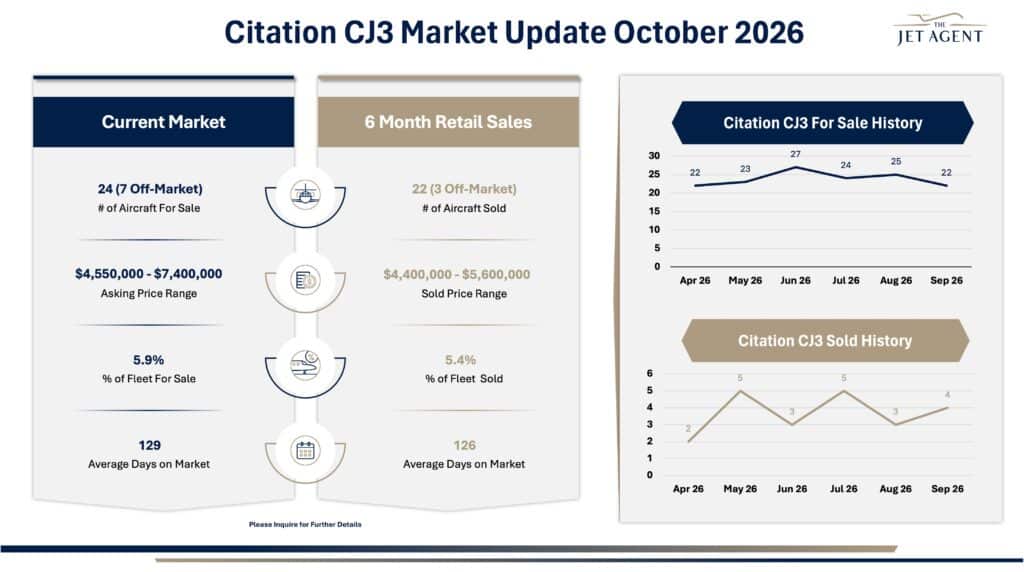
The CJ3 market currently has 24 aircraft available for sale, including seven off-market offerings, representing 5.9% of the fleet.
Inventory began the reporting period at 22 aircraft in April, increased to 23 in May, and reached a six-month high of 27 in June. Availability subsequently declined to 24 in July, increased slightly to 25 in August, and returned to 22 by the end of September.
This relatively stable inventory trend suggests that new listings are being absorbed without creating a sustained buildup of available aircraft. With fewer than 6% of the fleet currently offered for sale, buyers have a reasonable selection of aircraft, although opportunities may be more limited when considering specific configurations, equipment, and maintenance status.
Market Listings
Current asking prices range from $4.55 million to $7.4 million*, while completed transactions over the past six months have ranged from $4.4 million to $5.6 million.
*Note: there are two listings based in Brazil which are subject to VAT taxes and thus have artificially higher asking prices. Removing those two listings, the asking prices range from $4.55 million to $5.75 million, in line with what we have seen over the past few months.
Active listings currently average 129 days on market, compared with 126 days for aircraft sold during the reporting period. This narrow difference suggests that current inventory is spending approximately the same amount of time on the market as aircraft that have successfully transacted.
Sales Activity
Over the past six months, 22 CJ3 aircraft have sold, representing 5.4% of the fleet.
Monthly transaction activity has remained relatively consistent, with two sales in April, five in May, three in June, five in July, three in August, and four in September.
The market has recorded at least two transactions every month during the reporting period, with May and July producing the strongest results. September’s four completed sales represent a modest improvement over August and provide an encouraging indication of continued buyer participation heading into the fourth quarter.
With 22 aircraft sold over six months and 24 currently available, recent transaction volume is approaching the size of the existing inventory. This relationship suggests a market that continues to support appropriately positioned aircraft.
Key Takeaways
• 24 aircraft are currently available, including seven off-market offerings.
• Available inventory represents 5.9% of the fleet.
• Inventory declined from 25 aircraft in August to 22 in September.
• Current asking prices range from $4.55 million to $5.75 million (non-Brazilian options)
• 22 aircraft sold over the past six months, representing 5.4% of the fleet.
• Completed transactions ranged from $4.4 million to $5.6 million.
• Average days on market are 129 for active listings and 126 for completed sales.
• September recorded four sales, up from three in August.
Key Insight
The CJ3 market is active without being short of aircraft. Twenty-two sales over the past six months, including transactions every month, demonstrate consistent buyer participation. With 24 aircraft currently available, including seven off-market opportunities, buyers still have alternatives and sellers face meaningful competition. Current listings average 129 days on market versus 126 for sold aircraft, showing little separation in accumulated market time without establishing how quickly today’s inventory will sell.
The more consequential distinction is pricing. Asking prices extend to $5.75 million (non-Brazilian options), and reported transactions topped out at $5.6 million during the six-month period. That helps establish realistic expectations for CJ3 sellers to consider, but sellers asking above recent sales need aircraft-specific support for the premium. Equipment, engine coverage, maintenance position, total time, and condition must justify the difference.
For sellers, consistent sales provide a credible path to closing, but competing aircraft and completed transactions should guide pricing from the outset. For buyers, 17 publicly marketed aircraft plus seven off-market opportunities provide room for comparison. The strongest purchase is the aircraft offering the best combination of acquisition price, maintenance exposure, and equipment, not necessarily the lowest asking price.