The Citation CJ2 market enters October with inventory remaining relatively stable while sales activity continues to fluctuate. There are currently 20 aircraft available for sale, representing 8.5% of the fleet, while 15 retail transactions have been recorded over the past six months. Following a stronger August with four completed sales, September activity slowed to just one transaction. Inventory has remained below its July peak, suggesting that available supply is relatively balanced, although buyers continue to have several options. With current listings averaging more than 200 days on market, pricing and aircraft presentation remain important considerations for sellers heading into the final quarter of 2026.
Fleet Size and Availability
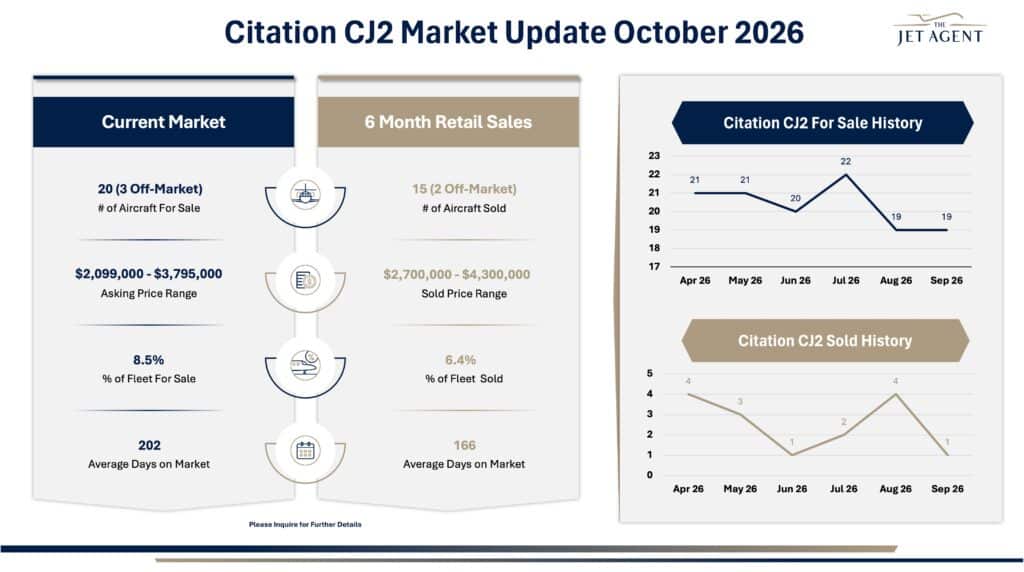
The CJ2 market currently has 20 aircraft available for sale, including three off-market offerings, representing 8.5% of the fleet.
Inventory began the reporting period with 21 aircraft in April and May, declined slightly to 20 in June, and reached 22 in July. Availability subsequently decreased to 19 aircraft in August and September, with the current market reporting 20 aircraft.
This relatively narrow inventory range suggests that supply has remained consistent throughout the past six months. However, with 8.5% of the fleet currently available, buyers continue to have a reasonable selection of aircraft to consider.
Market Listings
Current asking prices range from $2.099 million to $3.795 million, while completed transactions over the past six months ranged from $2.7 million to $4.3 million.
Aircraft currently listed for sale average 202 days on market, compared with 166 days for aircraft sold during the reporting period. This 36-day difference suggests that aircraft successfully completing transactions have generally spent less time on the market than those still available.
The broad range of asking prices reflects differences in model year, aircraft cosmetics, maintenance status, and equipment including Garmin panel upgrades. Notably, the upper end of the reported selling price range exceeds current asking prices, illustrating how the mix of aircraft sold can differ from those presently available.
Sales Activity
Over the past six months, 15 CJ2 aircraft have sold, including two off-market transactions, representing 6.4% of the fleet.
Monthly sales included four transactions in April, three in May, one in June, two in July, four in August, and one in September.
While August demonstrated that buyers remain active, September’s decline highlights the uneven pace of transactions. The market continues to produce sales, but activity has not established a consistent upward trend.
Key Takeaways
• 20 aircraft are currently available, representing 8.5% of the fleet.
• Inventory has remained between 19 and 22 aircraft throughout the reporting period.
• 15 retail transactions were recorded over the past six months, including two off-market sales.
• Asking prices range from $2.099 million to $3.795 million.
• Reported selling prices range from $2.7 million to $4.3 million.
• Current listings average 202 DOM, compared with 166 days for sold aircraft.
• September recorded just one sale, following four transactions in August.
Key Insight
The CJ2 remains a buyer-leaning market, with enough selection to support careful comparison and negotiation. That advantage is most useful when buyers evaluate the total investment required to bring each aircraft to their preferred standard.
For sellers, the priority is making the aircraft’s value clear from the outset. Garmin upgrades, engine program enrollment, complete records, and favorable maintenance status should be reflected in both pricing and presentation. Aircraft requiring additional investment need an asking price that acknowledges it. With sales occurring unevenly and marketing periods measured in months, accurate positioning matters more than waiting for a busier market.