The Citation CJ4 Gen2 market is continuing its transition from extreme scarcity toward more normalized pre-owned supply. Inventory has tripled since March while recent transaction activity has slowed, giving buyers considerably more choice than they had earlier this year. The market is not yet burdened by stale inventory, but the divergence between rising supply and slowing sales has become significant enough to watch closely as we move into the fall.
Fleet Size and Availability
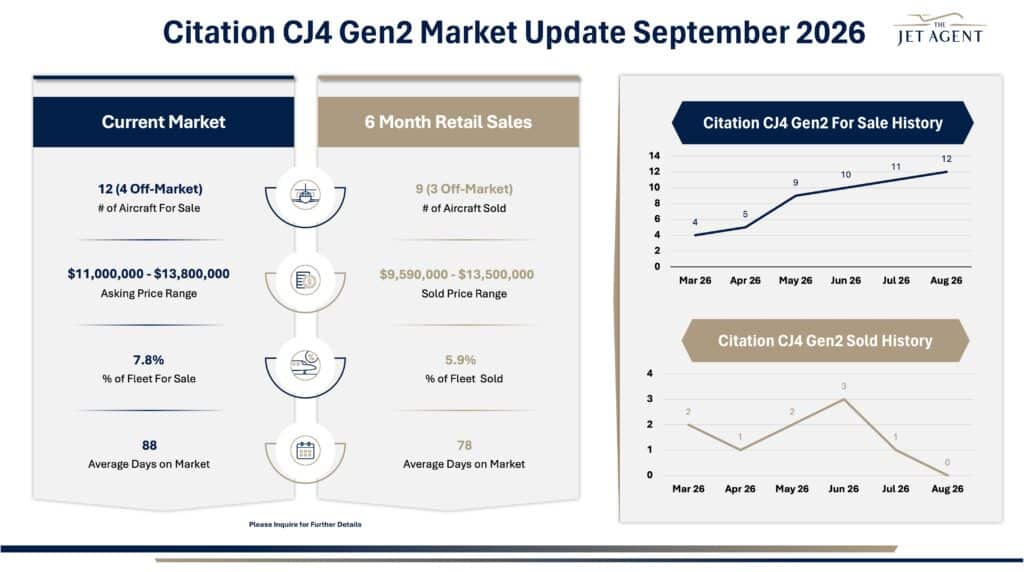
There are currently 12 Citation CJ4 Gen2s available for sale, including 4 off-market aircraft, representing 7.8% of the fleet.
Inventory has increased every month in the six-month period shown: four aircraft in March, five in April, nine in May, 10 in June, 11 in July, and 12 in August. That threefold increase materially changes the buying environment.
Earlier this year, buyers often had only a handful of opportunities to consider. Today they can compare multiple late-model CJ4 Gen2s based on total time, equipment, condition, cosmetics, damage history and price rather than feeling compelled to pursue whichever aircraft becomes available first.
Market Listings
Current asking prices range from $11.0 million to $13.8 million, while the six-month sold price range extends from $9.59 million to $13.5 million.
Aircraft currently for sale average 88 days on market, compared with 78 days for sold aircraft. The 10-day difference remains relatively small and indicates that today’s inventory has not yet developed into a backlog of stale listings.
That distinction is important. The market is becoming more competitive for sellers because supply has increased, but the data still reflects relatively fresh inventory rather than widespread distress.
Sales Activity
There were 9 retail sales over the past six months, including 3 off-market transactions, representing 5.9% of the fleet.
Two aircraft sold in March, one in April, two in May, and three in June before activity slowed to one transaction in July and none in August.
The timing is increasingly important: inventory rose from 10 aircraft in June to 12 in August while only one transaction occurred during July and August combined. If that relationship persists, current inventory will begin to age and pricing pressure could follow.
Key Takeaways
- 12 aircraft are currently available, including 4 off-market opportunities.
- Inventory has tripled from 4 aircraft in March to 12 in August.
- 7.8% of the fleet is for sale versus 5.9% sold during the past six months.
- 9 aircraft sold during the six-month period, including 3 off-market transactions.
- Current listings average 88 DOM versus 78 days for sold aircraft.
- No retail transactions were recorded in August.
Key Insight
The CJ4 Gen2 market has clearly shifted toward greater buyer choice, but it is still too early to characterize it as weak. The most important issue is no longer simply inventory growth; it is whether the new supply is absorbed before it begins to age. Current and sold-aircraft DOM remain close, suggesting the inventory buildup is still relatively fresh. For sellers, however, scarcity alone can no longer create urgency. If sales remain slow into the fall while inventory continues to expand, competition will intensify and pricing discipline will become increasingly important.